Bakersfield weather doesn't wait, and neither do we. AC or heat out? You jump the line. Call (661) 374-0624
Approved to offer Synchrony financing
Financing a New System
We offer the Synchrony Project Card on approved credit, including 0% interest for 60 months on installs. The flat published price is the same whether you finance or pay cash, because our prices already cover what financing costs us. Below you will find all three plans, including the one Synchrony requires us to carry and the reasons most people should not take it.
Which plan applies depends on the size of the job. You do not have to work that out yourself, we will tell you which one your work qualifies for before you apply.
installs0% for 60 mo
0% Interest, 60 Months
The one most people should take.
Equal monthly payments, and no interest accrues at all. Not deferred, not backdated, no catch at the end. Pay extra any time with no penalty.
A fixed rate until the balance is gone. No promotional window to miss, nothing that changes at a deadline, no backdated interest under any circumstances.
No interest only if the whole balance is cleared inside six months. Miss that and interest is charged backdated to day one. The minimum payment will not clear it.
The six-month plan, and why we would rather you didn't
Synchrony requires every Project Card merchant to carry one preselected promotion. Ours is a six-month plan, and it is deferred interest, which is not the same thing as 0% interest even though the advertising across this industry treats them as interchangeable.
Here is the difference, in one sentence. With a true 0% plan, no interest is ever charged. With deferred interest, the interest is accruing the whole time in the background, and it is waived only if you clear the entire balance before the promotional window closes. Miss it by a day, or by a dollar, and the whole accrued amount lands on your statement, calculated from the day of purchase at 26.99% for new cardholders.
Now the part that catches people. The minimum payment on this plan is 2.50% of the balance per month. Six of those payments add up to roughly 15% of what you owe. So a homeowner who makes every payment on time, never misses one, and assumes the promotion is handling it, arrives at month seven still owing about 85% of the original balance, and is then charged interest on the full amount going back to day one.
To actually clear the balance in six months you need to pay roughly six and a half times the minimum every month. If you can do that comfortably, this plan is genuinely free money and you should take it. If there is any doubt, take the 60-month plan at a true 0% instead, and pay it off early if you want to. There is no penalty for doing that, which is exactly why the shorter promotional term buys you nothing.
We are required to offer this plan. We are not required to let you walk into it without understanding it.
What financing does not change
The flat published price is the price whether you pay cash, card, or financing. Our prices already account for what it costs us to offer financing, so there is no surcharge for choosing it and no secret cash discount for skipping it. You get the same written quote either way, confirmed before work begins. Our published price list is the same page a cash customer reads.
It also does not change how we quote. About 60% of the systems we are asked to replace turn out to need only repairs, and the availability of financing has never once made that number go down. If your system can be repaired, we will tell you that, and a repair on the 5.99% plan will cost you a great deal less than a financed replacement you did not need. If you are holding somebody else's replacement quote, send it to us before you sign it.
Financing and rebates are separate things
Financing is how you pay. Rebates are money coming back. They stack, and the paperwork on both is our job rather than yours. Rebate applications, AHRI certificates, permit numbers, and itemized invoices formatted for submission all come from our office. The incentive landscape shifts constantly, so we check what is actually live the day we quote rather than quoting you a figure from last year. The honest 2026 rebate picture is here, including which programs are out of money.
How to apply
Applying takes a few minutes and Synchrony makes the decision, not us. We never see your score, your income, or your application details. There is no obligation attached: plenty of people get approved, hear what the repair actually costs, and never use the line.
You can apply before we visit, which is useful if you want to know your budget in advance, or at the kitchen table once you have the written quote in hand. Either order works.
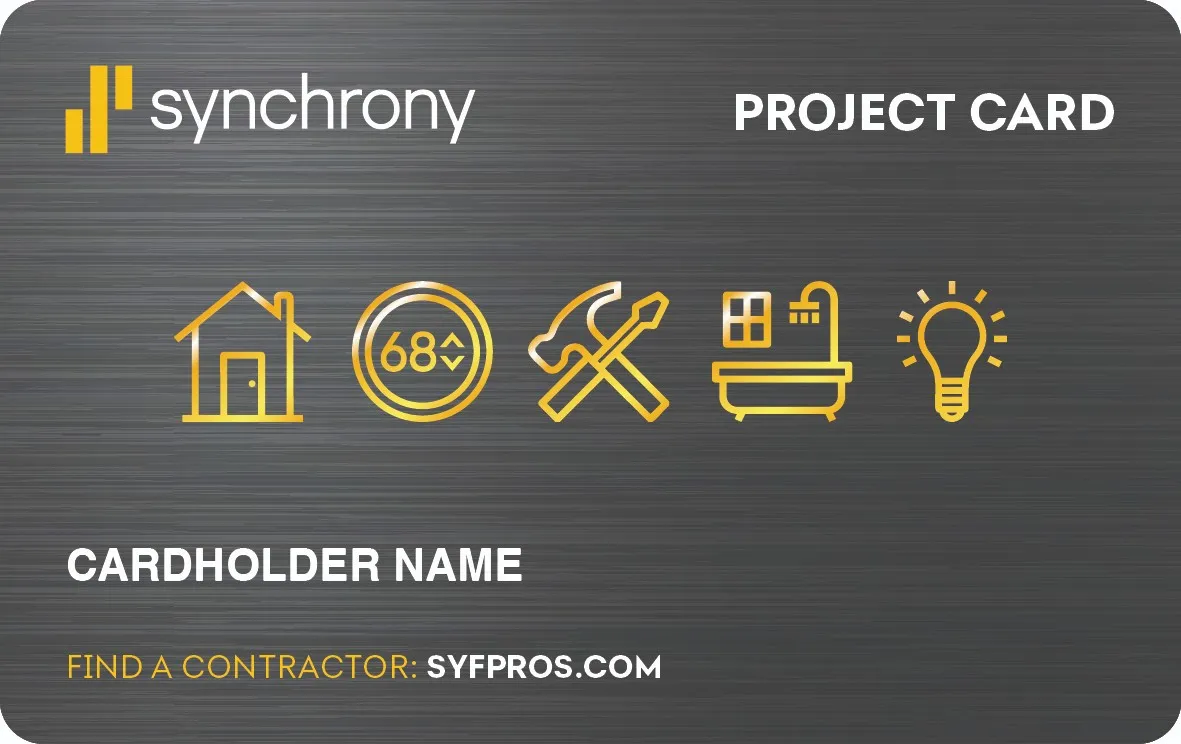
This is the card you would be applying for. Synchrony issues it and makes the credit decision.
The Synchrony Project Card, on approved credit. On installs we offer 0% interest for 60 months, where no interest accrues at all. On repairs and smaller work we offer a fixed 5.99% APR until it is paid off. Synchrony also requires us to carry a 6-month deferred interest plan, and that one has a catch we explain in plain language further up this page.
What is the catch with the 6-month plan?
It is deferred interest, not 0% interest. If the full balance is not paid off before the six months are up, interest is charged going back to the purchase date at 26.99% for new cardholders. The minimum payment will not get you there: it is 2.50% of the balance a month, so six minimum payments cover roughly 15% of what you owe. For most people the 60-month 0% plan is the better choice, and we will say so.
Does financing change the price?
No. The flat published price is the price whether you pay cash, card, or financing. Our prices already account for the cost of offering financing, so nobody pays a surcharge for choosing it and nobody gets a different number for paying cash. The quote is confirmed in writing before work begins, same as always. One charge is Synchrony's, not ours: a new cardholder may pay Synchrony a one-time $29 account activation fee when the first purchase posts to the account.
Will applying hurt my credit?
Applying results in a credit inquiry, which can affect your score. That is true of any credit application, and it is worth knowing before you apply rather than after. Synchrony makes the approval decision, not us. We never see your application details, your score, or your income.
Can I pay it off early?
Yes, on any of the plans, with no prepayment penalty. That matters more than it sounds: on the 60-month 0% plan you can pay extra whenever you like and clear it in a year or two if you want. There is no reason to take a shorter promotional term to accomplish that.
What if I am not approved?
Then we tell you straight and move on to what else is possible, which usually means repairing rather than replacing. About 60% of the systems we are asked to replace turn out to need only repairs, and that conversation is free. A financing decline does not change our price or how we treat the call.
Do you still handle rebate paperwork?
Yes, and that has not changed. Rebate applications, equipment documentation like AHRI certificates, permit numbers, and itemized invoices formatted for submission all come from our office. Incentives shift constantly, so we check what is actually live the day we quote. The honest current picture is on our rebates page.
No Interest for 60 Months* On qualifying heating and air conditioning installation purchases of $2500.00 or more after discounts made with your Synchrony Project Card. $29 account activation fee may apply. Equal monthly payments required for 60 months.
* Qualifying purchase amount must be on one receipt. Discounts may result in the qualifying purchase amount not being satisfied. No interest will be charged, and equal monthly payments are required on promo purchase until it is paid in full. The payments equal the initial total promo purchase amount divided by the number of months in the promo period, rounded up to the next whole dollar. These payments may be higher than the payments that would be required if this purchase was a non-promo purchase. During the last month(s) of the promo period the required monthly payment may be reduced due to the prior months’ rounding. Regular account terms apply to non-promo purchases. New Accounts as of 8/29/25: Purchase APR 26.99%. Min Interest Charge $2. One-time Account Activation Fee of $29 charged at time first purchase posts to account. Existing cardholders: See your credit card agreement terms. Subject to credit approval.
Financing is provided by Synchrony Bank on approved credit. Minimum monthly payments are required. For the 6-month deferred interest promotion: no interest will be charged if the promotional balance is paid in full within the promotional period; if it is not, interest is charged from the purchase date. For new cardholders, interest accrues at 26.99%. Existing cardholders should see their credit card agreement for their applicable APR. Promotional plan availability depends on the purchase amount. Wildflower Climate LLC is not the lender and makes no credit decisions. CSLB #1147883
Want the real number for your house?
Tell us what the system is doing and we will quote it in writing, flat, before anything gets financed. If it only needs a repair we will say that instead.